FHA Loans in Post Falls, ID
As little as 3.5% down with flexible credit — for repeat and first-time buyers alike.
Work directly with Jodie Barber, a mortgage broker with 30 years of experience serving Post Falls and all of Kootenai County.
Post Falls at a glance
More affordable Kootenai County alternative to CdA (~$483K), on the WA border — captures Spokane-commuter and veteran-relocation demand. Homes move quickly under ~$550K. Same N. Idaho veteran in-migration + VA thesis as CdA.
Serving Post Falls neighborhoods including Prairie, Riverbend, Downtown Post Falls, The Highlands.
Definition
What is an FHA loan in Post Falls?
An FHA loan in Post Falls is a low-down mortgage insured by the Federal Housing Administration and originated by a licensed broker — not a City of Post Falls grant. Kootenai County’s 2026 FHA one-unit limit is $572,700. Post Falls’ recent median is about $483,262 (Zillow ZHVI, May 2026), which leaves roughly $90,000 of room under that cap for a Prairie or Riverbend purchase. That gap is why FHA is a volume product here while Coeur d’Alene’s ~$575,000 median sits on the FHA line. Jodie Barber, NMLS #76185, sponsored by NEXA Mortgage, NMLS #1660690. Finance with Jodie is not a real estate brokerage.
Post Falls is the Kootenai city that Spokane commuters and Washington-border veterans can still cash-flow. Homes under about $550,000 move; the Highlands and newer Prairie plats are a different inspection than downtown’s older stock. This page is the FHA math for that border town — county limits, Idaho Housing’s 2026 repayable second, Fairchild-adjacent VA as the competing product, and how a buyer’s agent should write an Idaho contract for someone whose job is still in Spokane County.
Why Post Falls FHA is not a copy of Coeur d’Alene FHA
Same county, same $572,700 FHA cap, same $832,750 conforming baseline — different price. CdA’s median hugs the FHA ceiling. Post Falls sits ~$90,000 under it. That means FHA 3.5% down on a $483,000 house is about $16,900 before closing costs, and the appraisal has room before HUD’s cap becomes the problem. In CdA, a bidding war can push you out of FHA entirely. In Post Falls, FHA usually remains available unless you stretch into a custom Highlands build.
The buyer mix is different too. Post Falls captures Spokane-valley commuters who want Idaho’s property-tax math (effective ~0.49% plus the homeowner’s exemption) and Washington wages, plus the same veteran in-migration thesis as the rest of North Idaho. If you have VA entitlement, read the VA pages before you default to FHA. If you do not, FHA plus Idaho Housing assistance is the low-cash path.
USDA is generally not the in-town story. Post Falls’ core, like CdA’s, is in the ineligible urban pocket. Outer Kootenai and neighboring rural counties can be. Do not write USDA on a Prairie subdivision because the lot is a third of an acre.
Prairie, Riverbend, downtown, and the Highlands
Prairie is the growth direction — newer plats, HOA documents, and builder credits that can land on an FHA Loan Estimate as closing-cost help. Jodie will confirm the builder will do FHA before you spend a Saturday in a model home that only wants conventional.
Riverbend and the river-adjacent pockets raise flood and insurance questions that change escrow. FHA will finance in a flood zone with proper insurance; the payment is what changes. Downtown Post Falls mixes affordable older houses with FHA repair items (paint, heat, rails) familiar to anyone who has bought in a mill town.
The Highlands lean higher and more view-oriented. Some listings still fit under $572,700; some do not. When they do not, the file becomes conventional or VA. That is a Post Falls-specific fork, not a national FHA FAQ.
Idaho Housing in 2026 — repayable, not the old forgivable story
Idaho Housing and Finance Association down-payment and closing-cost help is now a repayable second mortgage, up to 8% of the sales price, with a small monthly payment next to the first. Household income must be at or below $170,000 on the headline product; some county/household-size limits are lower. Typical credit floors are about 620 conventional / 580 FHA. The Finally Home! education course is required. Buyers can sometimes get in with about $500 of their own funds when the second and seller credits do the rest — when they fit.
The discontinued forgivable/grant-style product is gone. If a well-meaning relative or an old blog told you Idaho still does “up to 10% forgivable,” that is stale. Jodie will run the current IHFA worksheet for Kootenai, not a 2024 flyer.
Gift funds remain allowed on FHA. Cross-state gifts from Washington parents are common in Post Falls. The paper trail still has to be boring and complete.
Working across the state line — job in Washington, house in Idaho
A lot of Post Falls FHA files have a Washington W-2 and an Idaho contract. That is fine. Qualifying income is still documented the usual way. The complications are practical: commuting time in residual/DTI conversations, Washington withholding versus Idaho income tax (Idaho has a flat 5.3% state income tax in 2026), and a buyer’s agent who is licensed to write the Idaho purchase agreement.
Jodie is licensed in both Washington and Idaho. She is not a real estate broker in either state. After pre-approval she can introduce a trusted local buyer’s agent who writes Kootenai contracts for Spokane-employed buyers. She will not introduce a named agent in marketing copy and will not claim Realtor® status.
Credit, MIP, and when conventional is cheaper
580 / 3.5% is the FHA published path; overlays apply. If your score is 700 and you can put 5% down, conventional may price better and PMI can drop at 20% equity. If your score is 620 and cash is tight, FHA plus a repayable IHFA second is often the file that actually closes. Jodie runs both. No rates on this page.
Keep learning
These guides live on the Learn hub — the same answers Jodie walks through on a call.
Credit, down payment, MIP.
How IHFA’s 2026 repayable second works.
When Post Falls buyers should switch.
The sequence for cross-state commuters too.
Generic process — no named agents.
If you have entitlement, compare VA.
Pre-approval for a border-town file, then a local intro
If your job is in Spokane and your house search is Post Falls, get the FHA number first so your buyer’s agent is not guessing at Idaho taxes and Kootenai HOA dues. Jodie will pre-approve you and can introduce a trusted local buyer’s agent. Finance with Jodie does not sell real estate. Call (425) 830-2240.
FHA Loans in Post Falls — local FAQ
- What is the FHA loan limit in Post Falls in 2026?
- Kootenai County’s FHA one-unit limit is $572,700. The conforming conventional limit is $832,750. Post Falls’ median around $483,000 sits well under the FHA cap, unlike Coeur d’Alene’s median near $575,000. Highlands or custom builds can still exceed $572,700 — then the conversation becomes conventional or VA.
- How much down payment is 3.5% on a typical Post Falls home?
- On a $483,000 purchase, 3.5% is about $16,905 before prepaid items and closing costs. Idaho Housing’s repayable second (up to 8% of price, income-capped) can reduce cash-to-close if you complete Finally Home! and fit the 2026 matrix. Gift funds are allowed on FHA with a proper letter. Not a commitment to lend.
- Can I use FHA if I work in Spokane and buy in Post Falls?
- Yes. Employment location does not have to match the property state. Jodie is licensed in Washington and Idaho. You will need an Idaho-capable buyer’s agent for the contract. She can introduce one after pre-approval. She is not a real estate broker.
- Is Post Falls USDA-eligible?
- The city core is generally not. USDA’s ineligible zones in North Idaho include the Coeur d’Alene and Post Falls urban pockets. Rural Kootenai and neighboring counties can be eligible. If you are shopping Prairie or Riverbend subdivisions, plan on FHA, VA, or conventional — not USDA.
- I am a veteran. Should I use FHA in Post Falls?
- Usually VA is better: $0 down, no monthly PMI, no FHA cap with full entitlement. Post Falls has no base; Fairchild AFB is about 35 miles west. Veteran in-migration is still a real VA demand driver. Pull a COE before you choose FHA out of habit.
- What happened to Idaho’s forgivable down-payment help?
- Discontinued. IHFA’s 2026 product is a repayable second, up to 8% of sales price, paid alongside the first mortgage. Income cap on the headline product is $170,000 (some limits lower). Do not budget for a forgivable 10% second. Jodie uses the current IHFA sheet.
- Should I call a realtor or a lender first in Post Falls?
- Lender first, especially if you are crossing the state line. A pre-approval that already includes Idaho property tax and HOA dues is what a listing agent wants to see. Jodie Barber, NMLS #76185, will write it and can then intro a trusted local buyer’s agent. No Realtor® claim.
- Can Jodie introduce a buyer’s agent in Post Falls?
- Yes, after a real pre-approval, to a local buyer’s agent who has closed FHA and IHFA files in Kootenai. No named agents on this page. You may bring your own. Finance with Jodie is not a real estate brokerage.
- Do FHA appraisals fail often on older downtown Post Falls houses?
- They fail when safety items fail: heat, roof, peeling lead paint, missing rails. Those are negotiable repairs or credits, not a reason to avoid the older grid. Newer Prairie construction usually has fewer MPR surprises and more HOA paperwork instead.
- How do Idaho property taxes affect an FHA payment versus living in Spokane?
- Idaho’s effective rate is about 0.49% with a homeowner’s exemption (50% of assessed value up to $125,000 on a primary residence). Washington’s effective rate is about 0.81% and there is no state income tax — but you will owe Idaho’s flat 5.3% income tax if you are an Idaho resident. Jodie prices the whole stack so a “taxes are cheaper in Idaho” rule of thumb does not underwrite the file by itself.
- Can I buy a Post Falls townhome or condo with FHA?
- Townhomes that are legally single-family attached are usually straightforward. Condos need HUD project approval or a valid single-unit approval. Jodie checks project status before you pay for an inspection.
- Will FHA mortgage insurance last the life of the loan?
- On most modern FHA loans with a low down payment, annual MIP stays until you refinance out or pay the loan off. Conventional PMI can drop at 20% equity. That is why Jodie shows a future-refi path on Post Falls files where the score and equity will likely improve.
- What credit score do I need for FHA in Kootenai County?
- HUD’s published path is 580 for 3.5% down (500–579 may need 10% down). Investor overlays can sit higher. If you are in the mid-600s with more cash, conventional may win. Jodie pulls credit with permission and will not guarantee an approval.
- Who is Jodie Barber on a Post Falls FHA page?
- A mortgage broker with about 30 years’ experience, NMLS #76185, sponsored by NEXA Mortgage, LLC (NMLS #1660690), licensed in Idaho and nine other states. Phone (425) 830-2240. Site financewithjodie.app. Verify her on NMLS Consumer Access. This is not a commitment to lend.
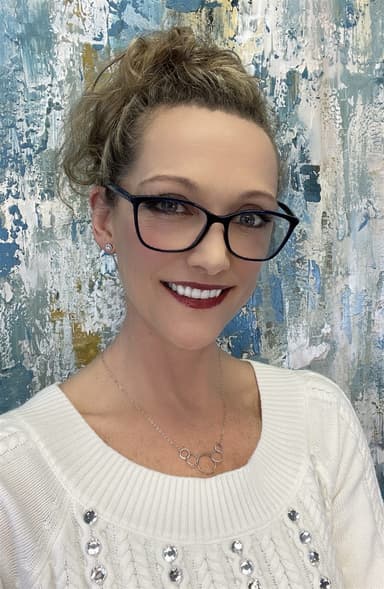
“Homeownership is a partnership.” Let's talk about your FHA loan in Post Falls. No pressure — just straight answers from someone who's done this for 30 years.